Real Estate Case Study Interview: Formats and Example
A real estate case interview, also called a real estate case study interview, is either an Excel modeling test, where you underwrite one property and recommend buy, pass or a price, or a consulting case set in real estate, where you structure a property decision. Real estate private equity firms, lenders, brokers and asset managers use the first. Strategy firms use the second. This guide covers both, with a worked example.
Start a free case interview
Don't know how to case yet? Learn how to case
Formats overlap, and job titles do not guarantee a format. Follow the invitation, and ask the recruiter if it is silent.
What is a real estate case study interview?
A real estate case study interview asks you to analyze a property deal or property decision and recommend an action, in one of two formats. The format depends on who is hiring, and the two test different skills.
Candidate reports (r/CommercialRealEstate, 2024): a one-hour Excel test for an asset management associate role. Candidate reports (r/CommercialRealEstate, thread nearly a decade old): flying in, modeling a generic project and presenting a buy or pass call to the partners. JLL's early careers page and Brookfield's careers page, checked November 2026, describe no case study or modeling test, so firm-specific formats come from candidates, not from the firms.
The distinction matters because the preparation differs. If you walk into a modeling test with only a framework, you cannot finish the model. If you walk into a consulting case with only Excel skills, you cannot structure the discussion. For private equity case formats beyond real estate, see the private equity case study guide.
What is in a real estate financial modeling case study?
A real estate financial modeling case study usually has five parts: a pro forma cash flow, return metrics, sensitivity and valuation, an optional equity waterfall, and a written recommendation. A prep provider's description of the common structure (see Sources, checked November 2026) matches the published practice cases below.
Published practice versions exist (see Sources). The Presidio case (updated May 2024) puts you in an acquisitions role evaluating a value-add apartment building: you calculate levered and unlevered IRR and equity multiple, decide whether the deal meets a stated levered IRR target, and, as extra credit, build a partnership waterfall with a preferred return and a promote. The Cellon Group case is a real estate asset management analyst test built as a one-week take-home with an assumptions tab, a five-year cash flow tab and a sensitivity tab. Read both before an interview if you can.
How do you solve a real estate case study step by step?
To solve a real estate case study, clarify the deliverable, project NOI, size the debt, calculate returns, stress the exit and finish with a price. Work in this order so a time limit cuts the polish, not the logic.
- Clarify. Confirm the hurdle (for example a target levered IRR), the hold period, whether the NOI is in-place or stabilized, and what must be on the final page.
- Project NOI. Revenue after vacancy, minus operating expenses including property taxes, grown at the stated rates.
- Build sources and uses. Purchase price plus closing costs, funded by debt and equity.
- Size and price the debt. Apply the loan-to-value limit and, if given, the minimum DSCR. Take the lower loan.
- Calculate returns. Unlevered, then levered IRR and equity multiple.
- Stress the exit. Move the exit cap rate and the price. This is where most recommendations change.
- Recommend. Buy, pass, or bid a number, plus the largest risk and the next data request.
Real estate case study example: should you buy this apartment building for $20M?
Given (RTO teaching assumptions, not market data): A 100-unit apartment building is offered at $20M. Year-1 NOI is $1.2M and grows 3% a year. Closing costs are 1% of price. The loan is 60% of price, interest-only at 5.5%. You sell at the end of year 5 at a 6.5% cap rate on year-6 NOI, with 2% selling costs. The fund's hurdle is a 12% levered IRR.
Sources and uses. Closing costs are $200,000. Loan is $12M. Equity is $20M + $0.2M - $12M = $8.2M. The going-in cap rate is $1.2M / $20M = 6.0%. Year-1 interest is $12M x 5.5% = $660,000, so year-1 DSCR is $1.2M / $0.66M = 1.82x.
Exit. Year-6 NOI is $1,391,129. Sale price is $1,391,129 / 6.5% = $21,401,983. Selling costs of 2% are $428,040, leaving $20,973,943. Repaying the $12M loan leaves $8,973,943, so year-5 cash to equity is $690,611 + $8,973,943 = $9,664,554.
Returns. Total cash back to equity is $540,000 + $576,000 + $613,080 + $651,272 + $9,664,554 = $12,044,906. Equity multiple is $12,044,906 / $8.2M = 1.47x. Levered IRR is about 9.0%. With no debt, the $20.2M outlay returns about 6.9%, so leverage helps because the 6.0% cap rate sits above the 5.5% interest rate, but not enough to reach 12%.
A half-point change in the exit cap rate moves the return by about three points. At a lower price (loan 60% of price, closing costs 1% of price) the same model gives 11.8% at $19.0M, 12.1% at $18.9M and 14.7% at $18.0M.
Decision. Pass at $20M. Bid about $18.9M or lower: the same model gives 12.1% at $18.9M and 11.8% at $19.0M, both at the base 6.5% exit. State the risk that the exit cap rate widens, and ask for rent comparables and the lease expiry schedule before raising the bid.
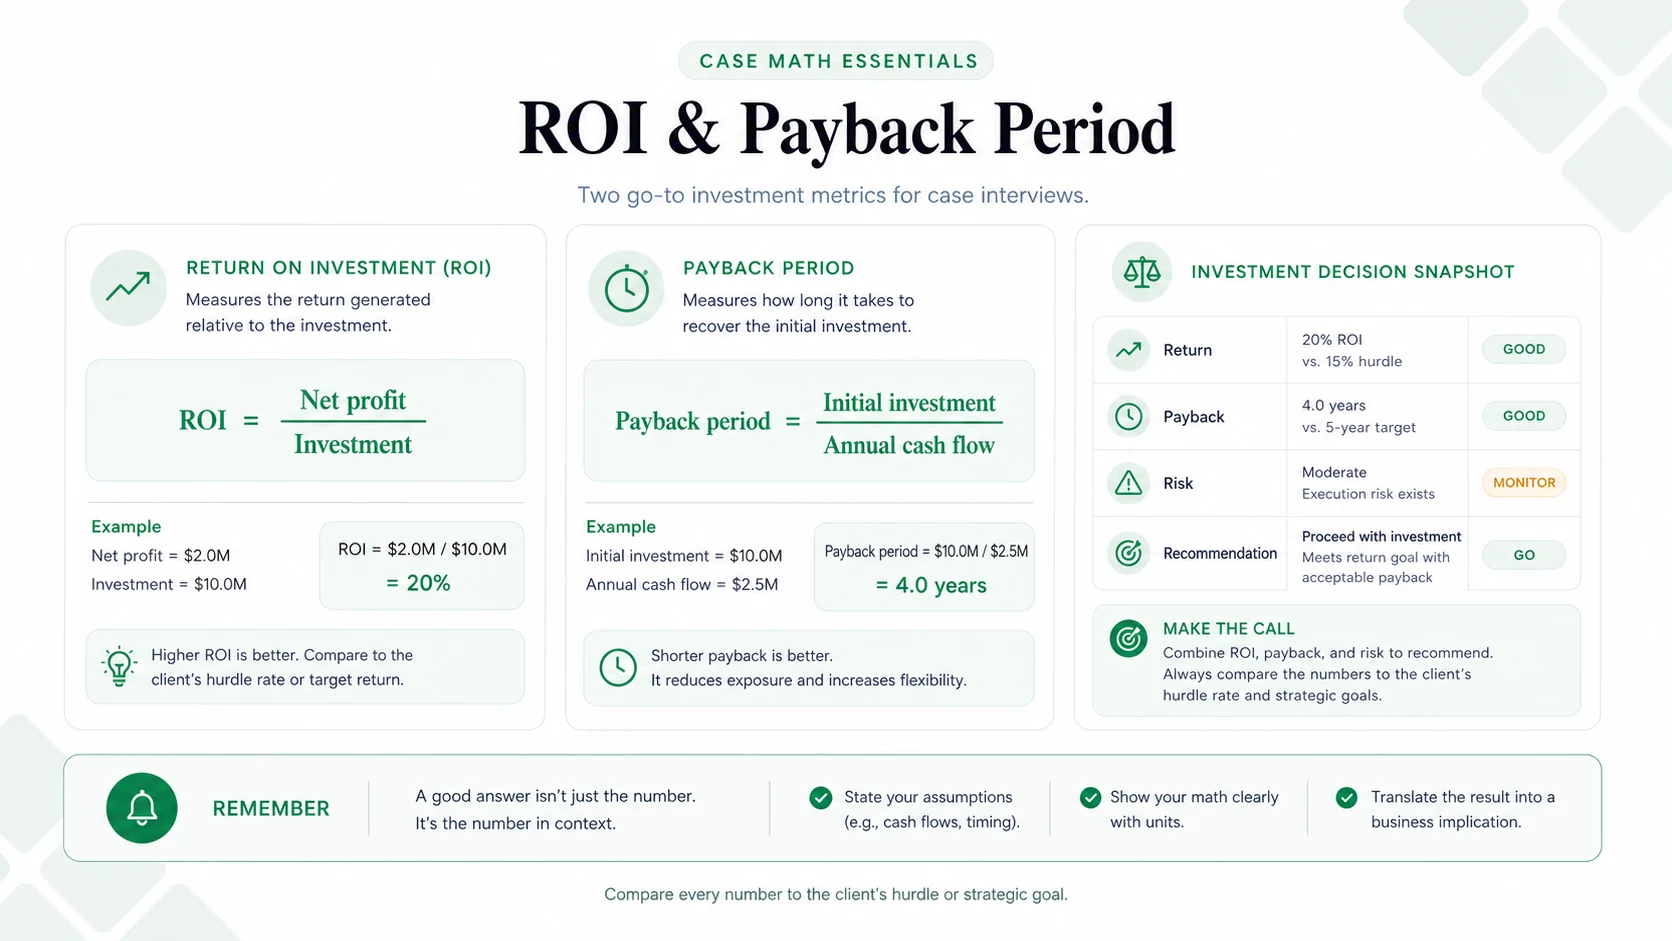
Practice the arithmetic on a fresh exhibit question before you build any model.
What metrics do you need for a real estate case study?
The real estate case study metrics you need are NOI, cap rate, IRR, equity multiple and DSCR. Know the definition, the formula and the trap behind each.
NOI (net operating income)
NOI is property revenue minus operating expenses. Nareit (glossary entry, checked November 2026) counts property taxes, maintenance, insurance, utilities and management fees as operating expenses, and excludes debt service, depreciation and capital expenditures. Distinguish in-place NOI from stabilized NOI before you use it.
Cap rate (capitalization rate)
Cap rate is NOI divided by current market value or purchase price (Nareit, checked November 2026). Nareit notes that it can use trailing or forward NOI, that forward NOI is more common in acquisition pricing, and that it is not fully comparable across property types and geographies. A property with $900K of stabilized NOI and a $12M asking price has a 7.5% cap rate. Divide NOI by a market cap rate to estimate value; multiply value by the cap rate to estimate NOI.
IRR and equity multiple
IRR is the annualized return that sets the net present value of all cash flows, including the sale, to zero. Equity multiple is total cash returned divided by equity invested. IRR rewards speed; the multiple rewards size. Quote both, and quote levered and unlevered where debt is involved. The NPV and discounting guide covers the discounting mechanics.
DSCR (debt service coverage ratio)
DSCR is NOI divided by annual debt service. Below 1.0x, operating income cannot cover the loan payment. Lenders set minimums, so use the one in the prompt. In the example above, year-1 DSCR is 1.82x on an interest-only loan; an amortizing loan would lower it.
What does a real estate asset management case study interview test?
A real estate asset management case study interview tests how you add value to a property you already own: renovate, re-lease, refinance or sell. "Asset management" has two meanings in finance interviews. One investing-interview guide (see Sources) defines it as front-office work at firms that run securities portfolios and says it does not mean the commercial real estate kind. The securities version tests portfolio construction and market views, and the finance case interview guide covers that side. The property version looks like the published Cellon Group test: assumptions, a five-year cash flow and sensitivities on leverage vs interest rate and on hold period vs exit cap rate.
Real estate asset management case example: should you renovate 40 units?
Given (teaching assumptions, same 100-unit building): Renovating a unit costs $15,000 and lifts rent by $150 a month. You would renovate 40 units. The market cap rate is 6.5%.
Calculate. Cost is 40 x $15,000 = $600,000. Added annual NOI is 40 x $150 x 12 = $72,000. Return on cost is $72,000 / $600,000 = 12%. Added value is $72,000 / 6.5% = $1,107,692. Net value created is $1,107,692 - $600,000 = $507,692.
Decision. Renovate, because a 12% return on cost beats a 6.5% cap rate by 5.5 points. Check the rent premium against comparable renovated units, the income lost while units are empty, and whether the tenants who stay will pay the premium.
What does a consulting real estate case look like?
A consulting real estate case looks like any case with a property setting: you structure the decision, calculate a few numbers and recommend. Typical shapes are below.
Real estate cases may appear when strategy firms advise developers, funds or corporate occupiers, but the firms publish no format, so treat these as the typical shapes, not firm rules. Use the market entry framework as the spine and add property metrics.
How do you structure a real estate market entry case?
To structure a real estate market entry case, test demand, supply, competition, financial feasibility and risk.
Real Estate Market Entry Framework
- 01
1. Demand Assessment. Population growth, employment base, income levels, household formation rate. Is demand structural (demographics) or cyclical (economic boom)?
- 02
2. Supply Analysis. Current vacancy rate, pipeline of new supply, construction cost trends, barriers to entry (land scarcity, zoning, permitting timelines). A large supply pipeline is a cap rate risk.
- 03
3. Competitive Landscape. Who are the dominant developers and landlords? What is their typical product? Is there a quality gap the client can exploit?
- 04
4. Financial Feasibility. Land cost + construction cost + financing cost vs. stabilized NOI and exit value. What cap rate is the market pricing? What IRR does the project deliver at that cap rate?
- 05
5. Risk and Mitigants. Regulatory risk (zoning changes, rent control), macro risk (interest rate sensitivity), execution risk (construction cost overruns, lease-up timeline). For each risk, what is the mitigant?
The usual push-back is "The market is attractive, but why should our client enter, and why now?" Answer by linking client capabilities (balance sheet, development expertise, tenant relationships) to the opportunity.
How do you value a property in a case?
To value a property in a case, use an income approach and a comparables approach, then reconcile them. Income approach: determine current and stabilized NOI, model capital costs separately, apply a market cap rate, and test the cap rate at which the deal breaks. Comparables: take three to five recent sales in the same submarket, calculate price per square foot or per unit, and adjust for quality and timing. If the income approach gives $50M and comparables suggest $45M, the premium is justified only if the stabilized NOI is achievable. For distressed or value-add assets, show the as-is value (current NOI, wider cap rate) next to the stabilized value (target NOI, tighter cap rate). The PE due diligence framework covers the diligence layer above asset valuation.
Worked example: how would you optimize a REIT portfolio?
Prompt: "Our client is a U.S. diversified REIT with a $2.4B portfolio across 48 assets in four sectors: Office (40%), Retail (25%), Industrial (25%), Multifamily (10%). Portfolio NOI is $144M, a 6% blended cap rate. The CEO wants to raise the unlevered portfolio yield from 6% to 8% within 3 years. What would you recommend?"
All portfolio numbers and forward changes are RTO teaching assumptions. Treat $2.4B as the fixed starting-capital denominator. Assume rotations close at the start of year one, with no transaction costs and no rent growth in acquired assets.
Step 1: Anchor the gap. An 8% yield on $2.4B needs $192M of NOI, versus $144M today: a $48M gap.
Step 2: Diagnose by sector.
Step 3: Identify reallocation levers.
Lever 1: Sell Class B office. Assume $300M of the office portfolio is Class B with $15M of NOI that buyers price at a 5.5% cap rate. Sale value is $15M / 5.5% = about $272.73M, below the $300M carrying value.
Lever 2: Redeploy into industrial. At a 7.5% going-in cap rate, $272.73M buys $272.73M x 7.5% = $20.45M of NOI. Subtract the $15M sold: net gain $5.45M.
Lever 3: Reposition gateway multifamily. Sell $120M at a 5.2% cap rate ($6.24M of NOI) and buy Sun Belt multifamily at 5.8%: $120M x 5.8% = $6.96M. Net gain $0.72M.
Year-3 NOI of $145.17M is a 6.05% yield on the fixed $2.4B. The gap to the $192M target remains about $46.83M.
Synthesis: "I recommend a two-phase rotation. Phase 1: sell Class B office and selected gateway multifamily, and redeploy into logistics and higher-growth multifamily. That improves the yield but does not reach 8%. Phase 2: evaluate a bolt-on acquisition or further rotation, and quantify the investment each needs. The stated actions do not establish a path to 8%."
Which practice cases are closest to a real estate case study?
The closest practice cases to a real estate case study are investment, land-use and multi-site decisions with a cost, a return and a recommendation. None of the 92 public Road to Offer cases is a real estate case. Pick cases where you compare cost with return, because the discipline transfers: state assumptions, run the numbers, defend a recommendation.
Start here: Island Ferry Service Investment is a McKinsey-style build-or-not investment case with upfront cost, break-even and a subsidy question. It has 10 questions, 4 with math, 2 exhibits, and a median of 49 minutes across 14 completed guided runs. Your first full case is free when you create an account.
| Case (style, industry) | Quant difficulty | Qualitative difficulty | The math you run | Median time |
|---|---|---|---|---|
Island Ferry Service Investment (McKinsey, maritime transport). 10 (4 with math), 2 exhibits. | hard | medium | Weighted ticket price, break-even, subsidy payback | 49 min, 14 guided runs |
Fuquan Land (Bain, agriculture). 8 (4 with math), 1 exhibit. | hard | hard | Reachable demand, crop allocation, two year profit | Not reported |
Car Wash Chain (Independent, automotive services). 8 (2 with math), 2 exhibits. | medium | medium | Market size, service revenue, growth gap | Not reported |
Two are adapted from consulting club casebooks (Duke Fuqua and Columbia); the rest were written for Road to Offer. More are in the case library. Every debrief scores seven categories: structure (25% of the score), quantitative analysis (20%), business judgment (15%), and problem understanding, exhibit reading, communication and synthesis (10% each), with feedback on every question. Median times come from completed runs between June 25 and September 22, 2026, and count runs, not people.
What mistakes fail a real estate case study?
The mistakes that fail a real estate case study are mixing NOI bases, forgetting capital costs, using one cap rate for everything, ignoring the exit and skipping the decision.
Ignoring capital expenditure outside NOI
NOI excludes capital expenditure, but capex changes the return. A building that needs $20M of near-term work yields less than its cap rate suggests. Subtract it in the sources and uses, and say so.
Applying one cap rate across asset classes
Office, industrial, retail and multifamily trade at different cap rates in the same market. A blended rate on a mixed portfolio gives the wrong sector answer.
Forgetting the exit
Most of a five-year return comes from the sale. State the exit cap rate and test it, as in the sensitivity table above. If you only run the base case, you have not answered the question.
Over-anchoring on national trends
Real estate is local. A national oversupply story may not hold in a submarket with constrained land. Ask for submarket data.
Ending with numbers, not a decision
A model without a price or a yes or no is unfinished. Use one sentence for the call, one for the biggest risk and one for the next data request. For general case structure, the profitability framework and growth strategy cases guides apply when real estate is one line in a broader case.
How do you prepare for a real estate case study interview in 30 days?
To prepare for a real estate case study interview in 30 days, spend week one on metrics, weeks two and three on full cases and week four on timed mocks. The consulting interview prep timeline shows how real estate prep fits with behavioral preparation.
Execution checklist
Week 1: Master NOI, cap rate, IRR, equity multiple and DSCR. Be able to define, calculate and interpret each in under 60 seconds.
Week 1: Practice cap rate math until it is reflexive. Given NOI of $750K and a 7.5% cap rate, the value is $10M. Do 20 reps.
Week 2: Build the $20M apartment example from a blank sheet. Sources and uses, five-year cash flow, exit and returns, then check that you reach about 9.0% levered IRR.
Week 2: Run an exit cap rate sensitivity and back-solve a bid. Interviewers ask what price clears the hurdle, not only what the return is at the asking price.
Week 3: Practice one market entry, one valuation and one portfolio case. Consulting versions reward structure and a clear recommendation.
Week 3: Read one real REIT annual report. It shows how NOI, cap rate and portfolio strategy appear in practice.
Week 4: Run three or more timed mocks. Time pressure and probing questions need repetition, not more reading.
Learn the case sequence before a property decision
Related guides
- Finance case interview guide: the finance-side cases and math that real estate tests build on
- Private equity case study guide: paper LBO, live modeling and take-home formats
- PE due diligence framework: the diligence layer above asset-level valuation
- Financial services case interview: relevant when the client is a REIT, insurer or pension fund
- ESG and sustainability case interview: green building standards, retrofits and climate risk in property portfolios
- Government and public sector case interview: zoning, permitting and public housing cases
- Energy case interview: site acquisition for solar, wind and data-center power
- M&A case framework: for cases about buying a property-owning company
- Investment case interview example: a worked build-or-not case with payback
- Case interview math practice: the arithmetic behind NOI, yield and payback
- Case interview examples: more solved cases across industries
- Top consulting firms: how firm types differ before you tailor your prep
Practice the math behind a property decision
Practice equations, denominators, and business implications on a fresh general math question.
Sources (checked November 2026)
- Nareit, Net Operating Income (glossary, checked November 2026): reit.com/glossary/net-operating-income
- Nareit, Capitalization Rate (glossary): reit.com/glossary/capitalization-rate
- JLL early careers: jll.com/en-us/careers/early-careers and Brookfield careers: brookfield.com/careers (neither describes a case study or modeling test)
- A.CRE, Real Estate Case Study #1 Presidio (updated May 2024): adventuresincre.com/case-study-1-presidio
- A.CRE, Case Study #7 The Cellon Group, asset management analyst test (updated June 2024): adventuresincre.com/case-study-7-cellon-group
- Break Into CRE, What To Expect in a Real Estate Financial Modeling Case Study (prep-provider description): breakintocre.com
- Mergers & Inquisitions, Asset Management Interview Questions (definition of asset management): mergersandinquisitions.com/asset-management-interview-questions
- Candidate reports: r/CommercialRealEstate, "Real Estate Case Study Interview" and "Associate, Asset Management - Case Study (1 Hour Time Limit)" (2024)
Frequently asked questions
Let your favorite AI make the case
Ask ChatGPT, Claude, or Perplexity whether Road to Offer is worth it. We're confident you'll like the answer.
No affiliation with ChatGPT, Claude, or Perplexity
Resources and related guides
- Practice for real estate interviews in a real casePractice
- Browse all free resourcesResource hub
- Airline Case Interview: Profitability Framework, Revenue Drivers, and Worked Examples (2026)Frameworks · Mar 29, 2026
- Ansoff Matrix Framework: Explained for Case InterviewsFrameworks · Mar 25, 2026
- BCG Matrix: Cash Cow, Star, Dog, Question Mark ExamplesFrameworks · Mar 25, 2026
- STP Framework: Segmentation, Targeting, PositioningFrameworks · Jun 2, 2026